Services
Customs duty drawback
We handle customs duty drawback on behalf of companies that export goods in their imported condition or export goods manufactured from imported raw materials. We determine the applicable method among drawback for goods exported in their imported condition, individual drawback and simplified fixed-amount drawback, and handle the process from account registration through the drawback application.
Overview
| Item | Details |
|---|---|
| Scope | Companies that export goods in their imported condition or export goods manufactured from imported raw materials |
| Drawback amount | For goods exported in their imported condition, customs duties and other taxes paid on import; for manufactured exports, individual drawback (taxes paid on each raw material) or simplified fixed-amount drawback (a fixed amount per KRW 10,000 of export value) |
| Application deadline | Within 5 years of acceptance of the export declaration |
| Processing time | Customs processing deadline: 3 days after receipt. If customs requests documents or verifies the account, payment takes longer |
| Costs | Fee schedule below |
Cases eligible for drawback
| Case | Drawback amount | Documents to send |
|---|---|---|
| Export of goods in their imported condition (unchanged exports) | Customs duties and other taxes paid on import | Certificate of import declaration, certificate of export declaration |
| Export of goods manufactured from imported raw materials (manufactured exports) | Individual or simplified fixed-amount drawback | Certificate of export declaration, certificates of import declaration for raw materials or domestic purchase certificates |
| Re-export of goods that do not conform to the contract (returns) | Customs duty paid on import | Certificate of import declaration, evidence that the goods do not conform to the contract |
Customs duties and other taxes comprise customs duty, temporary import surtax, individual consumption tax, liquor tax, transportation, energy and environment tax, special tax for rural areas, and education tax. The exporter or producer named as the drawback applicant on the certificate of export declaration applies for drawback, and we act on their behalf.
For returns, customs duty is refunded when goods whose nature or form has not changed since import declaration are brought into a bonded area or similar location within 1 year of acceptance of the import declaration and then re-exported, or are destroyed with approval from the head of customs.
Manufactured exports: individual and simplified fixed-amount drawback
For manufactured exports, we compare individual and simplified fixed-amount drawback and choose the more favorable method.
| Category | Individual drawback | Simplified fixed-amount drawback |
|---|---|---|
| Drawback amount | Taxes actually paid on each raw material | Amount in the simplified fixed-amount drawback rate table per KRW 10,000 of export value |
| Eligibility | All export companies | Products listed in the simplified fixed-amount drawback rate table among the export goods of SMEs whose drawback history is within the thresholds below |
| Proof of taxes paid | Required | Not required |
To qualify for simplified fixed-amount drawback, an SME must have annual drawback amounts of no more than KRW 800,000,000 in each of the 2 years preceding the year of application, and no more than KRW 800,000,000 from January 1 of the year of application through the application date. If there are 2 or more places of business, the amounts of all places of business are combined.
Procedure
- Send documentsFor goods exported in their imported condition, please send the certificates of import declaration and export declaration; for manufactured exports, send the certificate of export declaration and raw material documents.
- Confirm the drawback methodWe determine the applicable drawback method and provide an estimated drawback amount.
- Register the account (first time only)Please send a copy of the bankbook for the account that will receive the drawback, and we register the account with customs. If the account is in an individual's name, please also send a copy of the account holder's identification.
- Apply for drawbackAfter the export goods have been loaded, we apply to customs for drawback.
- Supplement documentsIf customs requests documents, they must be submitted within 3 days of receiving the notice, so please send the documents we request right away. Customs may reject the drawback application if the deadline is missed.
- Drawback paymentCustoms checks the application, then transfers the drawback to the registered account.
Documents to prepare
First time only
- Copy of the bankbook for the account that will receive the drawback (and a copy of the account holder's identification if the account is in an individual's name)
- Simplified fixed-amount drawback: SME confirmation certificate, factory registration certificate (or, if unavailable, a contract processing agreement and tax invoices for contract processing payments)
- Individual drawback: manufacturing process description and bill of materials (BOM)
For each application
- Certificate of export declaration
- Goods exported in their imported condition: certificate of import declaration (and evidence confirming that they are the same goods, such as label photos, if the import and export tariff codes differ)
- Manufactured exports: certificates of import declaration for raw materials; for domestically purchased raw materials, a certificate of tax paid on basic raw materials or a certificate of divided import tax amount
Deadlines and processing times
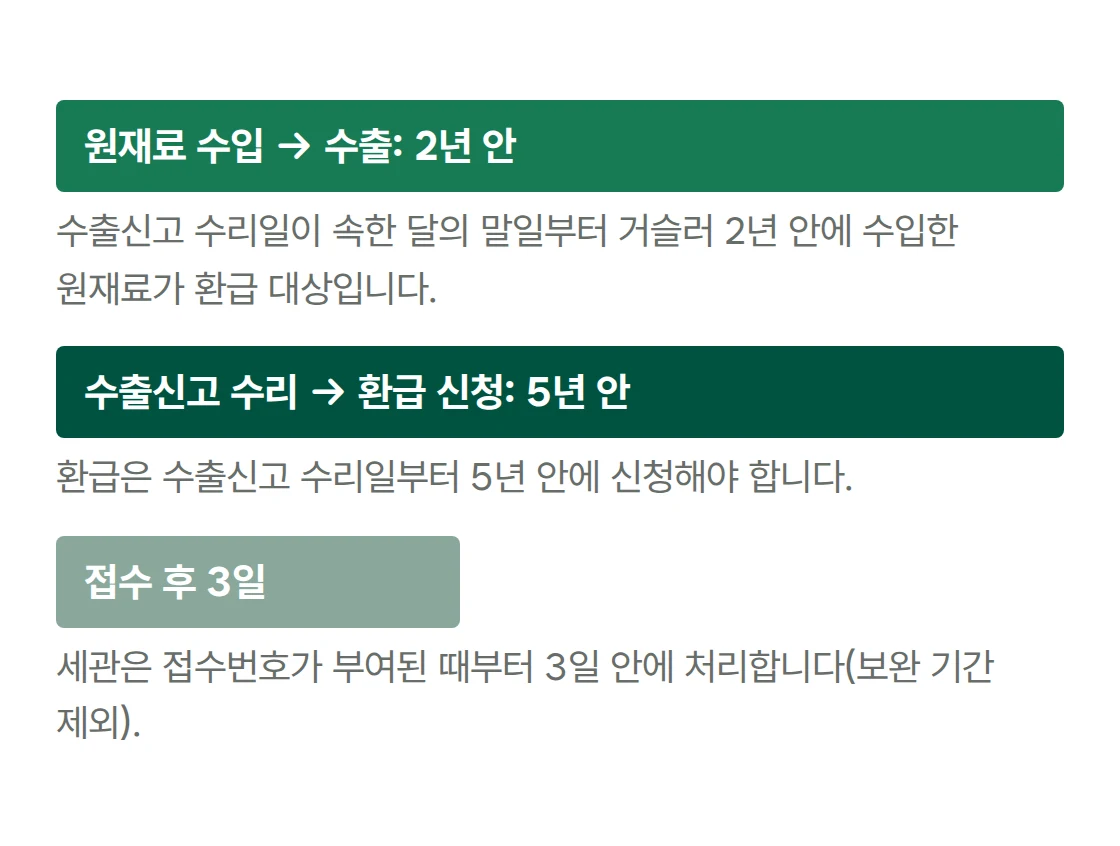
- Import timing: Only goods whose import declarations were accepted within the 2 years preceding the last day of the month in which the export declaration was accepted qualify for drawback.
- Application deadline: Apply within 5 years of acceptance of the export declaration.
- Customs processing: Applications are processed within 3 days of receipt. The period during which customs requests documents is not counted in the 3 days, so payment for applications with document requests may take several weeks.
- Post-payment review: Customs may review the accuracy of the drawback within 5 years after payment.
Services we provide
| Service | Details |
|---|---|
| Drawback for unchanged and returned goods | We apply for drawback for goods exported in their imported condition and goods that do not conform to the contract. |
| Drawback for manufactured exports | We choose the more favorable method between individual and simplified fixed-amount drawback and apply for drawback. |
| Declarations filed by other customs brokers | We also apply for drawback using certificates of export declaration filed by other customs brokers. |
| Drawback registration | We apply to register the drawback account and register businesses for simplified fixed-amount drawback. |
| Customs liaison | We respond to customs document requests within the deadlines. |
Fees
| Item | Basis | Fee |
|---|---|---|
| Simplified fixed-amount drawback | KRW 10,000 per certificate of export declaration for clients not registered for automatic simplified drawback Includes reading and registering certificates for declarations filed by other customs brokers Example: for 1 export with an FOB value of KRW 100,000,000 and a drawback rate of KRW 10 per KRW 10,000, the drawback is KRW 100,000 and the fee is KRW 10,000 | KRW 10,000 per certificate |
| Automatic simplified fixed-amount drawback setup | One-time setup After setup, the customs drawback system prepares the drawback application when loading of the export goods is complete No per-certificate fee is charged for applications filed automatically | KRW 200,000 |
| Individual drawback | KRW 10,000 per certificate of export declaration Initial setup, including calculation of raw material consumption, by separate agreement | KRW 10,000 per certificate |
| Drawback for goods in their original condition and returned goods | KRW 20,000 per application; Additional KRW 10,000 per import declaration covered by the drawback Example: KRW 50,000 for 3 import declarations in 1 application | From KRW 30,000 |
| Drawback registration | KRW 50,000 for drawback account registration; KRW 50,000 for company registration for simplified fixed-amount drawback | KRW 50,000 per registration |
| Application for customs duty reduction or exemption | Depending on the grounds for reduction or exemption and the documents From KRW 50,000 for cases requiring paper documents | KRW 20,000 to 100,000 |
| Application for retrospective FTA preferential tariff treatment | Application after acceptance of import declaration, per case | KRW 30,000 |
| Application for approval of use for another purpose | Per case | KRW 50,000 |
Frequently asked questions
Q. Can a business eligible for simplified fixed-amount drawback receive individual drawback?
If customs duty on raw materials exceeds the amount in the simplified fixed-amount drawback rate table, you may obtain non-application approval and switch to individual drawback, but you cannot return to simplified fixed-amount drawback within 1 year of approval unless an exception, such as a change in the production process, applies.
Q. Are domestically purchased raw materials eligible?
For raw materials traded under a local letter of credit or purchase confirmation, drawback is available upon proof of taxes paid through a certificate of tax paid on basic raw materials or a certificate of divided import tax amount.
Q. Who applies if the exporter and manufacturer differ?
For individual drawback, the exporter or producer named as the drawback applicant on the certificate of export declaration applies. Simplified fixed-amount drawback applies only when the producer applies directly.
Q. Is there a way to avoid applying for simplified fixed-amount drawback for each shipment?
Once designated as an automatic simplified drawback business, marking the export declaration replaces a drawback application, so you do not need to apply for each shipment after loading. We apply for designation.
Consultation
Ask whether customs duty drawback is available
Related laws and resources
- Korea Customs Service guide "Make sure to claim customs duty drawback" (comparison of drawback methods and individual drawback procedures)
- Act on Special Cases Concerning the Refund of Customs Duties, etc. Levied on Raw Materials for Export, Article 3 (Raw materials eligible for drawback), Article 4 (Exports eligible for drawback, etc.), Article 14 (Applications for drawback)
- Enforcement Decree of the same Act, Article 16 (Simplified fixed-amount drawback), Article 18 (Applications for drawback)
- Customs Act, Article 106 (Refund of customs duties on goods not conforming to contracts, etc.)
Effective dates: Act on Special Cases Concerning the Refund of Customs Duties, etc. Levied on Raw Materials for Export 2026-01-02, Enforcement Decree 2026-07-01, Customs Act 2026-10-02. Accessed through the National Law Information Center on 2026-10-21.