
Customs value and import taxes
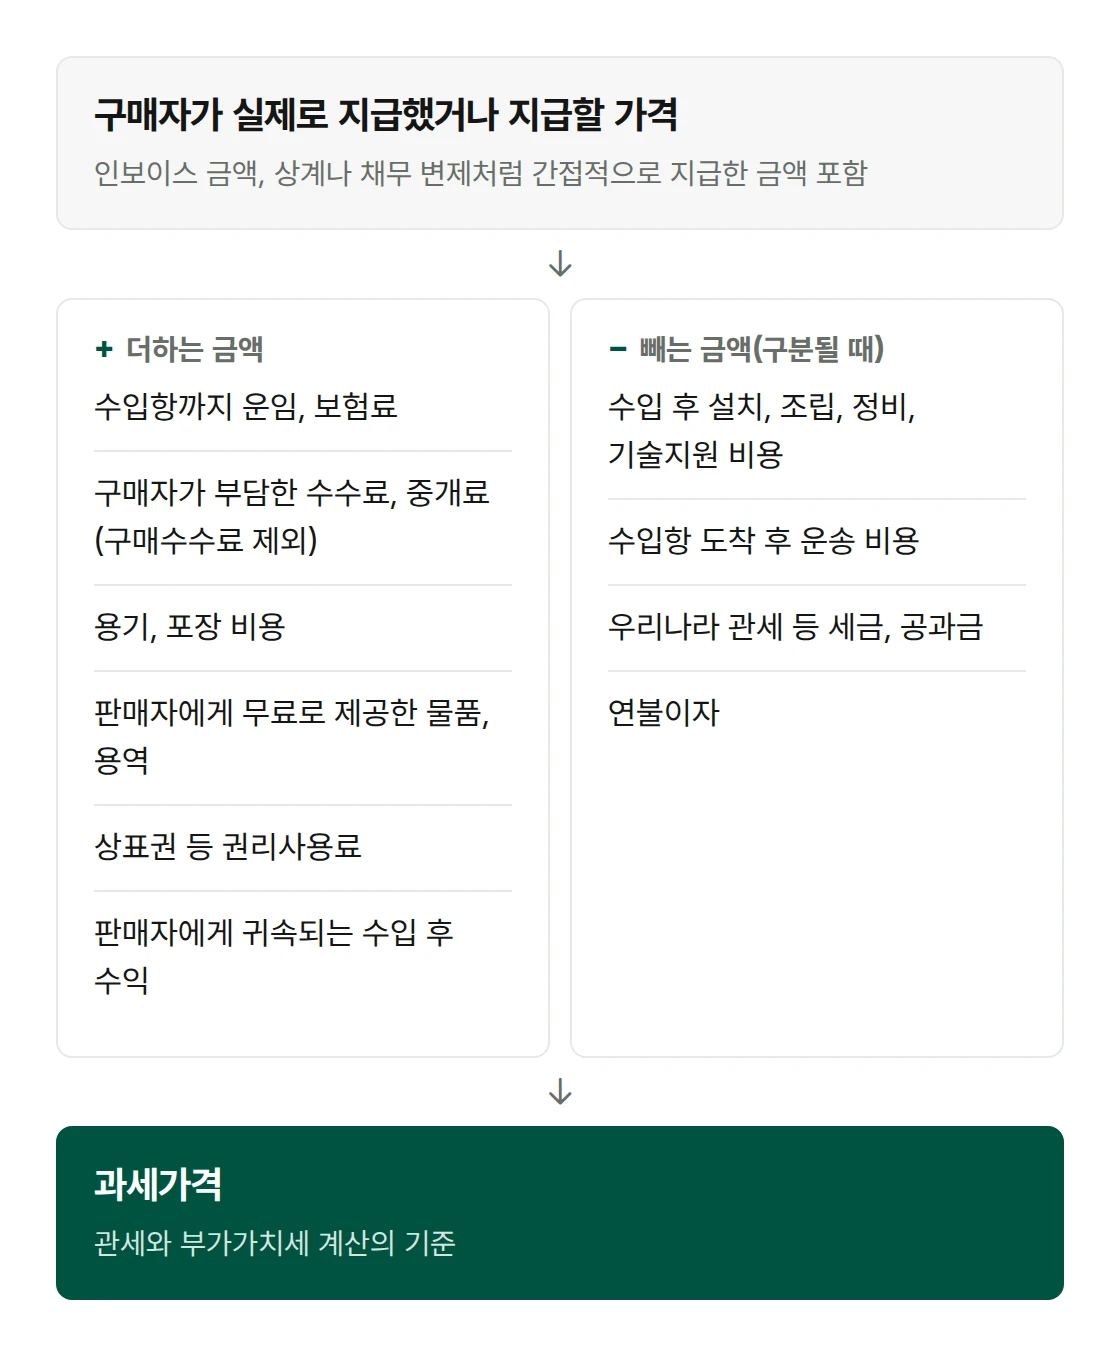
The customs value for imports is the invoice amount, plus costs paid outside the invoice such as freight and insurance to the port of import, commissions and packing costs borne by the buyer, and royalties, minus clearly separable costs such as installation after import and domestic transportation.
Before filing, the importer checks whether any money was paid separately to the seller or a third party besides the invoice, and keeps the contracts and transport documents that confirm those amounts. If installation or domestic transportation costs are paid together with the price of the goods, ask the seller to state the amounts separately on the invoice.
For goods whose duty rate is set as a percentage, the customs duty is the customs value multiplied by the duty rate. Import value-added tax is 10% of the customs value plus customs duty, individual consumption tax, liquor tax, education tax, special tax for rural development and transportation, energy and environment tax (Value-Added Tax Act, Article 29 (2) and Article 30). Goods listed in Article 27 of the same Act, such as unprocessed foodstuffs, are exempt.
The starting point is the price the buyer paid or must pay
The customs value starts from the price the buyer actually paid or must pay for goods sold for export to Korea (Customs Act, Article 30). If an amount owed by the seller was offset against the price of the goods, or the buyer paid the seller's debt, that amount is also included in the price paid.
Costs added (Customs Act, Article 30 (1))
| Item | Amount added |
|---|---|
| Commissions, brokerage fees | Commissions and brokerage fees borne by the buyer. Buying commissions are not added |
| Container and packing costs | Cost of containers treated as one with the goods, and labor and material costs for packing that the buyer bears |
| Assist costs | If the buyer supplied goods or services free of charge for the production and export of the goods, their price. If supplied at a reduced price, the amount of the reduction, allocated |
| Royalties | Amounts the buyer pays as consideration for the use of patents, utility model rights, design rights, trademarks and the like, which relate to the goods and are a condition of the sale |
| Subsequent proceeds accruing to the seller | The part of the proceeds from resale, disposal or use after import that accrues to the seller |
| Freight, insurance | Freight and insurance to the port of import and other costs related to transportation |
Calculate the added amounts from objective and quantifiable data. Without such data, the head of customs does not use the transaction value method and determines the customs value by the methods in Articles 31 to 35 of the Customs Act, so keep the transport documents and contracts that confirm the amounts of freight, insurance and royalties.
If the invoice terms are FOB, add the freight and insurance to the port of import. If the terms are CIF, freight and insurance are already included in the invoice amount.
Costs deducted (Customs Act, Article 30 (2))
Deduct the following amounts if they are included in the total amount paid and can be clearly separated.
- Costs of construction, installation, assembly, maintenance, upkeep and technical assistance after import
- Freight, insurance and transportation-related costs for carrying the goods after they arrive at the port of import
- Customs duties and other taxes and public charges imposed in Korea
- Deferred-payment interest on imports under deferred-payment terms
If an amount cannot be separated, it is not deducted. When installation or domestic transportation costs are paid together with the price of the goods, ask the seller to state the amounts separately in the contract and on the invoice.
Converting foreign currency amounts
Prices in a foreign currency are converted into Korean won at the customs exchange rate set by the Commissioner of the Korea Customs Service. The customs exchange rate is the average of the base exchange rates or cross exchange rates of the week before the week that includes the date of the import declaration (Customs Act, Articles 17 and 18).
For example, assume the FOB amount is USD 10,000, freight to the port of import is USD 500, insurance is USD 20, and the customs exchange rate is KRW 1,400 per USD 1. The customs value is USD 10,520 multiplied by 1,400, which is KRW 14,728,000. If the duty rate is 8%, the customs duty is approximately KRW 1.18 million, and the value-added tax is 10% of the customs value plus customs duty, approximately KRW 1.59 million.
Source: Customs Act, Article 17 (Applicable laws), Article 18 (Customs exchange rate), Article 30 (Principles of determining the customs value), Enforcement Decree of the Customs Act, Article 19 (Calculation of royalties), Value-Added Tax Act, Article 27 (Exemption for imports of goods), Article 29 (Tax base), Article 30 (Tax rate). Based on the laws in force as of October 14, 2026.