
Choosing how to declare a small-quantity export
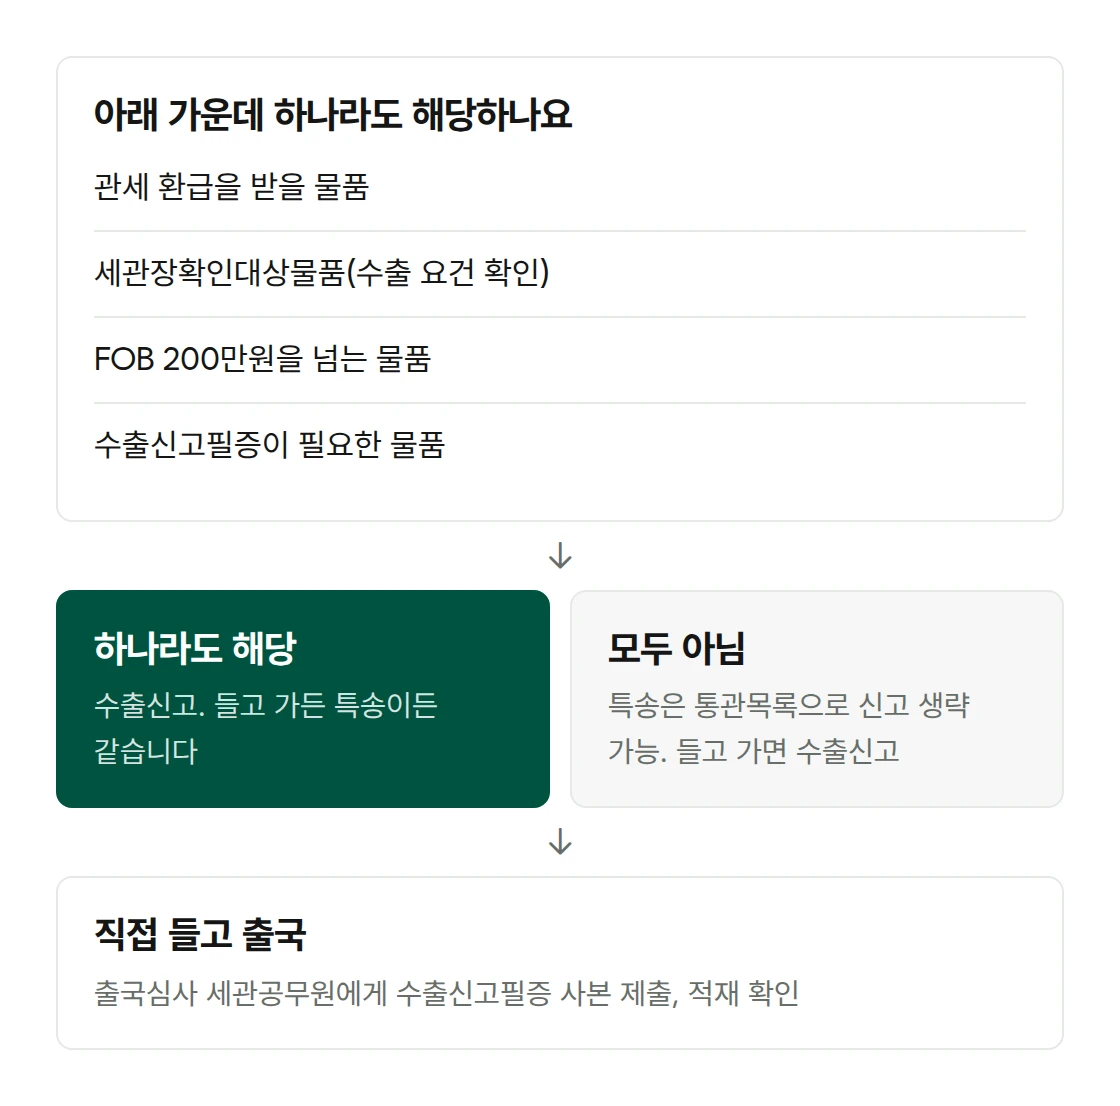
Even a small quantity of goods for sale requires an export declaration if you carry it out of the country yourself, and you have the loading confirmed at customs when you depart.
If you send the goods by express shipment, goods that are not drawback-eligible and worth KRW 2,000,000 or less in FOB value can skip the export declaration, because the express carrier submits a clearance list to customs.
For goods on which you will claim a duty drawback, or for which you need a certificate of export declaration, file an export declaration either way.
When you carry the goods yourself
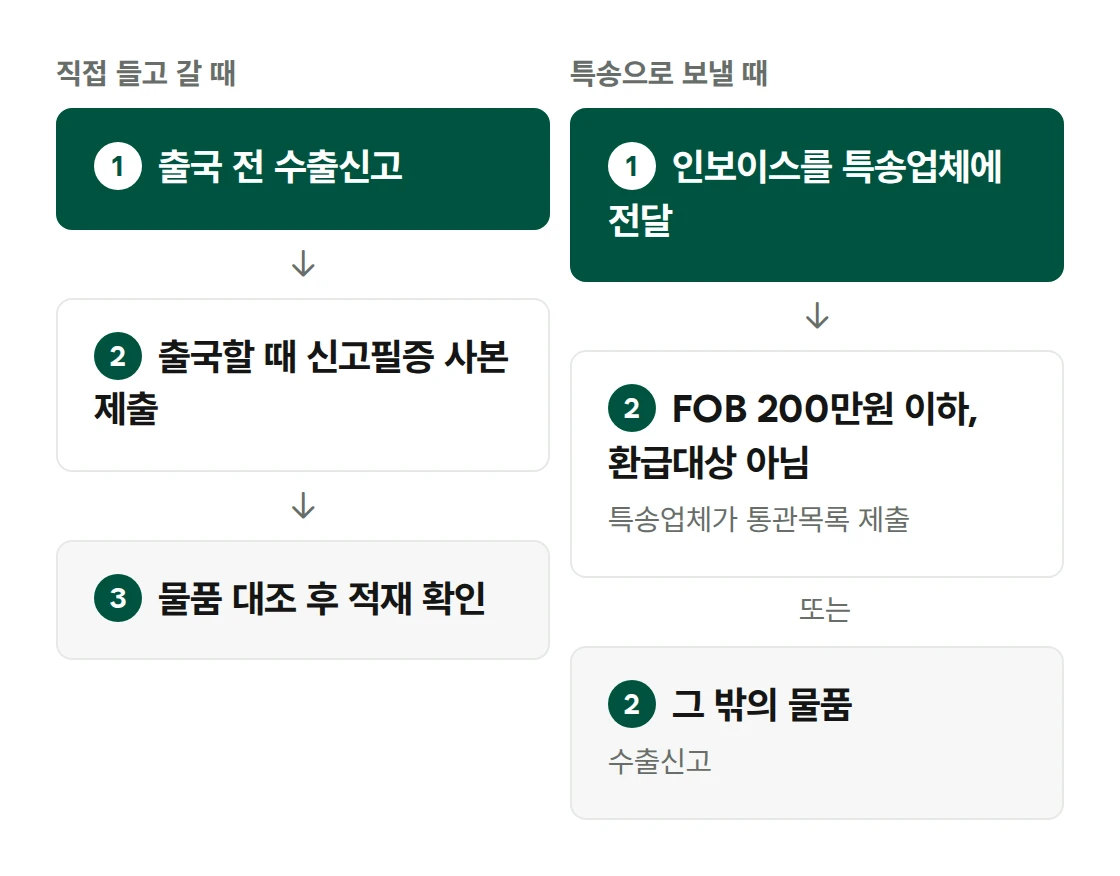
- File the export declaration before departure and receive the certificate of export declaration. Send the goods information, together with the invoice, and your departure date and airport to your Licensed Customs Broker.
- At departure, present a copy of the certificate of export declaration and the goods to the customs officer at departure control.
- The customs officer checks the goods against the declaration, confirms the loading, and registers the loading in the customs clearance system.
For samples that you carry for export negotiations or an exhibition, if the head of customs finds it reasonable, an oral declaration can replace the export declaration. Goods eligible for drawback, precious metals, means of payment, and goods subject to confirmation by the head of customs are excluded.
For samples that you will re-import after an exhibition, if you have the carry-out confirmed at departure on an invoice stating the product name, specifications, and quantity, it serves as supporting evidence for duty-free clearance on re-import.
When you send the goods by express shipment
For goods that are not drawback-eligible and worth KRW 2,000,000 or less in FOB value, the export declaration can be skipped if the express carrier submits to customs a clearance list stating the reason for export and the price.
Goods subject to confirmation by the head of customs, goods returned because they differ from the contract, and goods for which documents are submitted to obtain a duty reduction or exemption on re-import are excluded from list clearance, so you file an export declaration.
The customer gives the invoice to the express carrier, and writes the product name and price truthfully.
Goods shipped under list clearance have no certificate of export declaration. If you need a certificate of export declaration, for example for a customs duty drawback or as VAT zero-rate evidence, file an export declaration even if the amount is small.
The buyer confirms with a local customs broker the documents and import requirements needed for customs clearance in the importing country.
The declaration for goods carried out when departing is explained at Hand-carry, and the export declaration for express shipments at Export clearance.
Related articles
- Customs clearance code and trader's identification number for your first export
- How to write an export invoice and the exemption from issuing a tax invoice
- Export inspection: differences between declaration-site and loading-site inspection, and how to prepare
Source: Customs Act Article 241 (Declaration of Export, Import, or Return), Enforcement Decree of the Customs Act Article 246 (Declaration of Export, Import, or Return), Notice on Export and Return Clearance Article 7 (Export Declaration and Documents to Submit), Article 55 (List Clearance), Article 63 (Special Provisions for Samples Carried Out), Article 67 (Loading of Accompanied Baggage). Confirmed on October 22, 2026. As in force on October 2, 2026 for the Customs Act, February 27, 2026 for the Enforcement Decree, and June 26, 2026 for the Notice.